Get the right experience for you. Please select your location and investor type.
IMPORTANT NEWS: Transition of investment management responsibilities (excluding the Worldwide strategies)
First Sentier Group, the global asset management organisation, has announced a strategic transition of Stewart Investors' investment management responsibilities to its affiliate investment team, FSSA Investment Managers, effective Friday, 14 November close of business EST.

Asia Pacific All Cap
Originally launched in December 2005, this equity-only strategy aims to deliver long-term capital growth by investing in between 30-60 companies in the Asia Pacific region, including Australia and New Zealand but excluding Japan. As with all of our strategies, we are looking for businesses that are well positioned to contribute to, and benefit from, sustainable development.
Strategy highlights: a focus on quality and sustainability
- We invest in high-quality companies with exceptional cultures, strong franchises and resilient financials. How we pick companies >
- Our approach is long-term, bottom-up, high conviction and benchmark agnostic
- We focus on capital preservation as well as capital growth – we define risk as the permanent loss of client capital
- Companies must contribute to sustainable development. Portfolio Explorer >
- We avoid companies linked to harmful activities and engage and vote for positive change. Our position on harmful products >
Quarterly update
Strategy update: Q3 2026
Asia Pacific All Cap strategy update: 1 July - 30 September 2026
Market review
Asian equities ended a turbulent quarter relatively flat, after a sell-off in July, a rebound in August and relatively muted performance in September. Singapore was the best-performing country, mainly driven by strong performance in financials such as Oversea-Chinese Banking Corp (OCBC) and DBS Group. Hong Kong rose on the back of improving sentiment towards China’s AI ecosystem, which, combined with attractive valuations and strong mainland capital flows, fuelled a broad re-rating of large-cap technology platforms. On the negative side, South Korea was worst hit by the pullback in AI-related stocks in July, as concerns over the sustainability of hyperscaler capital expenditure mounted, and investors started to unwind leveraged positions in chipmakers and other technology companies. India also declined, as oil prices again rose above the US$100 per barrel mark due to Middle East supply disruptions.
Performance review
The largest contributor to performance over the period was Oversea-Chinese Banking Corp (OCBC), which reported strong earnings results, mainly driven by wealth management. The new CEO aims to maintain the bank’s growth ambitions, with a focus on strengthening its franchise in Hong Kong, Singapore and across ASEAN domestic markets.
The second largest contributor to performance was MediaTek, which continued to benefit from growing optimism around its AI ASIC business and strong sales growth momentum. In addition, NVIDIA and MediaTek announced that they would deepen their relationship across AI datacentre infrastructure, with NVIDIA investing US$3.5bn in MediaTek’s convertible bonds.
The third largest contributor to performance was Lite-On Technology, which reported better-than-expected earnings results, with operating profits ahead of forecasts on strong data centre demand. Management has lifted guidance on full-year sales growth, based on order visibility from AI clients, with strong momentum expected to roll forward into next year.
On the negative side, SK Hynix, Samsung Electronics and Silergy declined alongside a broader sell-off in technology companies. Concerns about high valuations and unfunded capital expenditure plans fuelled negative market sentiment and led to the unwinding of margin trades in these crowded sectors.
New purchases over the quarter
Bajaj Finance is India’s leading non-bank financial company (NBFC). Bajaj Finance began with vehicle finance and consumer durable lending and has now expanded into other areas; this presence across different market segments makes it distinctive among India’s NBFCs. The company has a solid track record of high return on assets, strong growth and resilience through crises such as the Covid-19 pandemic. It is currently undergoing changes which we believe should support future growth, such as increased use of AI to deliver productivity gains.
Luxshare Precision is an electronics contract manufacturer that counts Apple as its largest client. In recent years the company has been diversifying its business away from smartphone assembly towards automotive components and segments related to AI data centre infrastructure, such as connection components, optical components and cooling systems. Luxshare’s disciplined management and track record of scaling new businesses give us confidence in its prospects.
Complete sales over the quarter
The only complete sale over the quarter was Chroma, which had rerated – we had been trimming, and there was only a small toehold position remaining. While Chroma had delivered a strong track record over the past 10 years, with investments into R&D and consistent execution contributing to the strong growth profile we see today, our fair market valuation (FMV) suggested little upside at current market valuations.
Looking forward
Asian equities continue to offer a compelling combination of structural growth and improving earnings prospects. We see attractive opportunities in India, supported by favourable demographics and rising incomes, while in China, the shift towards higher-value industries and globally competitive businesses continues to create a rich opportunity set for long-term investors.
In the near term, markets are likely to be influenced by the path of US interest rates, global trade policy developments, Chinese policy support and the sustainability of AI-related capital expenditure. But we believe valuations across much of Asia remain reasonable relative to long-term earnings potential, particularly in parts of China and ASEAN where sentiment remains subdued.
Meanwhile, though returns have been driven by a narrow group of AI beneficiaries over the past two years, there are encouraging signs that market leadership is beginning to broaden. We are confident that our portfolio holdings – high-quality businesses with strong governance, resilient balance sheets and durable competitive advantages – should continue to deliver attractive shareholder returns in the long run.
Source for company information: First Sentier Group and company data. This stock information does not constitute any offer or inducement to enter into any investment activity. Portfolio data shown is from representative strategy accounts of the strategy shown above. Named new investments disclosed relate to holdings with a portfolio weight over 0.5%. It is not a recommendation or solicitation to purchase or invest in any fund. Differences between the representative account-specific constraints, currency or fees and those of a similarly managed fund or mandate would affect results.
Download a PDF copy
Select Strategy update to produce a report. You can then download a copy of the report by clicking on the button.
You can build a bespoke report for all our strategies on the full Quarterly update report.
Strategy update: Q2 2026
Asia Pacific All Cap strategy update: 1 April - 30 June 2026
Market review
Asian equities staged a strong recovery in Q2, following news of the Middle East ceasefire in April and subsequent peace deal in June. Semiconductors and companies related to the AI supply chain rebounded after a spate of strong earnings results as well as higher capex guidance from US hyperscalers (ensuring a strong demand outlook). In this environment, Information Technology was the best performing sector over the quarter, as well as Korea and Taiwan on a country level. On the negative side, Indonesia was the worst performing country due to the ongoing overhang from the potential MSCI downgrade. China and Hong Kong were also weak as domestic activity disappointed, and concerns about cross-border capital controls weighed on sentiment towards offshore China.
Performance review
Similar to Q1, the top three contributors to performance over Q2 were beneficiaries of the AI boom. While these are high-quality, well-managed companies, AI demand has boosted their valuations to expensive levels, and they would likely be affected by a slowdown in capital expenditure (capex) among Big Tech firms. We have taken advantage of the recent strength to trim our position in all three.
The largest contributor to performance over the period was Samsung Electronics, which continued to benefit from strong demand for its high bandwidth memory (HBM) stacks and dynamic random-access memory (DRAM) chips. Given the supply shortages, memory pricing is on an up-trend and is expected to remain strong until at least 2028. Added to this, customers have become more interested in signing longer-term 5-year supply deals to secure memory chips, which increases earnings visibility, reduces cyclicality and enables more effective capacity planning.
The second largest contributor to performance was MediaTek amid optimism around the potential growth in its AI ASIC business. Its partnerships with Google and other major technology firms to create custom chips for AI applications are expected to contribute a greater proportion of operating profit going forward.

The third largest contributor to performance was TSMC, which rose after reporting strong earnings results. Its position as the most technically advanced fabricator of leading-edge semiconductor chips is clear, despite whispers of rising competition from Intel and Samsung. TSMC enjoys more than 90% share of leading-edge nodes, and with AI demand driving higher profits and strong guidance for the year ahead, the company is accelerating capital expenditure plans to try and narrow the gap between its supply and customer demand. Meanwhile, tight supply should support higher prices and feed into gross margins and profitability, with good visibility through to 2027-28.
On the negative side, Tencent was the largest detractor from performance. The company posted earnings results that were broadly consistent with forecasts, as weaker-than-expected gaming revenue was offset by robust performance in its online advertising business. We believe the decline in the share price reflects ongoing concerns over the perceived slow pace of Tencent's monetisation of AI. Nevertheless, we believe the company's vast WeChat ecosystem and access to data will provide it with strong advantages in the AI era.
The second largest detractor from performance was AIA Group, which declined despite solid earnings results. Although its Thailand business dragged on performance – as it fell from a high comparable base in 2025 – the Value of New Business grew strongly in other markets, particularly Mainland China and Hong Kong. We believe the weakness is due to concerns about greater regulatory clampdown on cross-border capital flows, which would affect new business from mainland China visitors.
The third largest detractor was Jardine Matheson. The company held its inaugural investor day, which broadly reiterated its commitment to disciplined capital allocation and to improve operations in existing businesses, which should lead to improvements in total shareholder returns. We believe the recent weakness is due to its exposure to certain sectors and geographies, especially Indonesia which is facing a number of headwinds.
New purchases over the quarter
SK Hynix is a leading semiconductor company in Korea. It has a solid position in the DRAM and NAND memory markets, but more importantly, it is the leader in High-Bandwidth Memory (HBM) that is now being optimised for AI use. While traditional DRAM and NAND memory has become commoditised and commands little pricing power, HBM is built around annual contracts, long lead times, and high capital intensity. Customers like NVIDIA must commit to volumes well in advance, and vendors must make investment decisions based on those commitments. This order-based model introduces more predictability and customer stickiness (though it also increases execution risk and dependence on a few large buyers).
Lite-On Technology is a leading Taiwanese power supply maker which has benefited from the explosive growth in AI data centres. As server power and power density continues to rise, Lite-On should benefit from higher selling prices and improved margins.
ICICI Bank is one of the largest private sector banks in India. We believe the structural opportunity for high-quality private banks like ICICI Bank lies in its ability to gain share from inefficient state-owned banks. While the bank had highly aggressive lending practices and a risk-taking culture in the past, the appointment of CEO Sandeep Bakshi in 2018 signalled change after a long and tumultuous history. Under Mr Bakshi’s leadership, the bank has undergone a cultural transformation and now fosters a more long-term oriented, conservative and risk-aware mindset. The results are evident in the bank’s performance, and it now boasts industry-leading asset quality and growth metrics. ICICI has invested significantly in technology (digitisation and automation) over the last year, which has led to higher costs, but as revenue growth improves, there is potential for operating leverage to grow. Meanwhile, asset quality is currently the best it has been over the last three decades.
Complete sales over the quarter
We continued to sell out of lower conviction holdings, consolidating the portfolio into companies where we have more confidence in the management, franchise and financials. Complete sales over the quarter included Singapore Telecommunications, a communications technology group, Ayala Corp, a Philippine conglomerate, Bank of the Philippine Islands, the oldest bank in the Philippines, and Sundaram Finance, a non-banking finance company (NBFC) in India.
We also sold out of Alibaba on concerns about its multipolar business structure and lack of strategic stability. Alibaba continues to suffer from organisational fatigue driven by constant restructuring; and while it admittedly represents the most credible Chinese parallel to the US "Big 4" hyperscalers, we remain sceptical of the company’s true "North Star".
Looking forward
We remain optimistic on the outlook for Asian equities. While the Middle East conflict, and its impact on energy prices, has led to elevated short-term market volatility, our quality bias means that our holdings should remain fundamentally resilient. Although Asia is heavily dependent on the Middle East for its energy needs, the emerging markets universe has historically operated in a more inflationary and volatile environment, and we have taken this into consideration in our stock selection.
In the long run, we believe Asia should continue to benefit from the shift towards higher value services-led growth, digital transformation and the ongoing financialisation across the region. Valuations look attractive in comparison to developed markets like the US, while low ownership of Asian equities in global portfolios provides a good backdrop for absolute returns as global liquidity flows eastwards.
As markets start to broaden from their narrow focus on AI, we believe quality businesses owned in the portfolio should do well. We have invested in companies with high-quality management who think long term and counter-cyclically, operating in industries with deep moats that support predictable and strong returns on capital. They are running businesses with solid pricing power due to strong brands, high switching costs, or strong network effects, and with conservative balance sheets where cash exceeds debt. We are confident that their strong fundamentals will translate into attractive shareholder returns in the long run.
Source for company information: First Sentier Group and company data. This stock information does not constitute any offer or inducement to enter into any investment activity. Portfolio data shown is from representative strategy accounts of the strategy shown above. Named new investments disclosed relate to holdings with a portfolio weight over 0.5%. It is not a recommendation or solicitation to purchase or invest in any fund. Differences between the representative account-specific constraints, currency or fees and those of a similarly managed fund or mandate would affect results.
Strategy update: Q1 2026
Asia Pacific All Cap strategy update: 1 January - 31 March 2026
Market review
Asian equities declined over the quarter, as rising geopolitical risks weighed on investor sentiment. At the end of February, the US and Israel initiated a military campaign against Iran, leading to rapid destabilisation across the Middle East region. This pushed energy prices sharply higher and reignited concerns about sticky inflation and rising interest rates.
Despite the volatility in March, Korea held on to gains made earlier in the year and was again the best performing market over the quarter. Thailand rose after recent election results suggested a more stable political environment ahead. On the negative side, Indonesia declined after MSCI warned it may downgrade the country to frontier status and Moody’s Ratings downgraded the country’s credit rating outlook to negative. Regulators have since acted on some aspects and have until May 2026 to implement changes to satisfy MSCI. India declined on concerns about its energy dependence on the Middle East, mixed corporate earnings results and a weakening rupee.
Performance review
The top three contributors to performance over the period were beneficiaries of the AI boom. While these are high-quality, well-managed companies, AI demand has boosted their valuations to expensive levels, and they would likely be affected by a slowdown in capital expenditure (capex) among Big Tech firms. We have therefore taken advantage of the recent strength in their share prices to trim our positions in all three names.
The largest contributor to performance over the period was Samsung Electronics, a leading manufacturer of memory and semiconductor chips. The company posted record profits thanks to soaring AI-related demand and tight supply for its high-bandwidth memory chips. Samsung started shipping its next-generation HBM4 chip in February – having reportedly agreed higher prices compared with the previous model – positioning the company to capture a larger share of fast‑growing AI server demand. On the other hand, high DRAM and NAND prices look less sustainable in the medium term as it is already causing demand destruction in consumer electronics products.
The second largest contributor was Taiwan Semiconductor Manufacturing (TSMC), the leading semiconductor foundry, as recent earnings results were stronger than expected. With AI demand driving higher profits and strong guidance for the year ahead, the company announced new capital expenditure plans to try and narrow the gap between its supply of advanced nodes and customer demand.
The third largest contributor to performance was Chroma ATE, a leading Taiwan-based supplier of testing equipment for semiconductors, power generation and electric-vehicle batteries, among other applications. The company's full-year 2025 earnings beat analyst expectations, showing a sharp increase in profits. This was largely thanks to Chroma's leading position in semiconductor testing and the production of power-testing equipment for AI data centres, which means it is a key beneficiary of the Big Tech capex cycle. The market has also welcomed its move into new areas such as co-packaged optics (CPO), a next-generation technology for connecting chips using light rather than copper wires.
On the negative side, Tencent, the biggest social media network and online gaming company in China, declined after the company announced it would reduce its share buybacks to support accelerated investment in AI. We recently met the company to discuss its AI strategy, and came away with our conviction strengthened. Tencent has been hiring experts in the field and is developing an in-house LLM. Over the longer term, we believe Tencent should benefit from AI thanks to its unique advantages: a massive user base across WeChat, games and payments; rich first-party data; and integrated advertising and content systems. We have been using the recent weakness to build up a meaningful position in the company.
The second largest detractor from performance was HDFC Bank, as the bank continued to face a challenging operating environment and improvement in net interest margin has been slower than expected. The resignation of the chairman also led to concerns. However, we have spoken with the management and joined a call with the new interim chairman Keki Mistry, who we respect. We feel comfortable about the governance and the quality of its franchise – in particular, its deposit franchise and underwriting culture/capability remain solid and a standout amongst banks. Valuations have declined to levels not seen before, even during the Global Financial Crisis or the Covid-19 pandemic, and we find this to be very attractive, given HDFC’s leading deposit franchise and pristine balance sheet. We believe returns can improve and book value can compound at a mid-teens rate which is attractive in absolute terms
The third largest detractor was Trip.com, China's dominant online travel platform, with around 70% market share. The company fell sharply in January following news of an anti-monopoly investigation by Chinese regulators (the company is cooperating fully with the investigation). This was compounded by investor fears that large language models (LLMs) could disrupt its business. However, the company’s proven track record in handling the real-world complexities of payments, cancellations and customer service, not to mention relationships with hundreds of thousands of hotels and other travel providers, give it key competitive advantages. Recent earnings results have been positive, and we expect Trip.com to benefit from continued travel demand in China.
New purchases over the quarter
XCMG Construction Machinery is a leading construction equipment maker with market-leading positions across its comprehensive product portfolio. Due to legacy state ownership, lack of alignment and core businesses being kept outside of the ListCo, XMCG had not performed well in the past, but the recent mixed shareholding reforms (in 2022) provided a positive catalyst for change. XCMG has introduced an employee share ownership plan (ESOP) and is focused on improving its operational efficiency and shareholder returns. We believe XCMG can become a much stronger company in time, which could drive meaningful earnings growth.
Fuyao Glass is a leading auto-glass maker with a large and growing export business. The company is an industry leader, with a strong competitive moat and track record. As automobiles turn into “intelligent mobile terminals”, technology is being integrated into auto-glass – such as car windscreens with futuristic heads-up displays, panoramic skylight glass, and coated glass to block the harmful effects of ultraviolet and infrared radiation. Fuyao’s products are lighter, more durable and more energy-efficient than peers, which puts it in a good position to win contracts from global car manufacturers and continue to increase its share of content per car. While a slowdown in EV sales is a key risk, we believe Fuyao’s current valuation is attractive and offers decent risk/reward.
Complete sales over the quarter
We continued to sell out of expensive holdings in India where the risk/reward looks poor compared to other, more compelling opportunities. Complete sales over the quarter included Info Edge, a leading recruitment and real estate classifieds platform; and Marico, a leading consumer business with a dominant share in branded coconut oil.
While both companies have attractive franchises with decent growth prospects and are helmed by management teams we like and respect, we would want to own them at cheaper valuations. We believe an important contributor to returns over the longer term is to stay disciplined on valuations.
We also sold out of Tata Consultancy Services (TCS) and Tech Mahindra, as the changing face of technology is leading to headwinds for IT services companies in general. This has led to revenue deflation, which makes it even harder for large companies to adjust. The valuation was not cheap, factoring in these concerns, and the risk/reward did not seem favourable.
Looking forward
We remain optimistic on the outlook for Asian equities. While the Middle East conflict, and its impact on energy prices, will likely result in elevated short-term market volatility, our quality bias means that our holdings should remain fundamentally resilient. Although Asia is heavily dependent on the Middle East for its energy needs, the emerging markets universe has historically operated in a more inflationary and volatile environment, and we have taken this into consideration in our stock selection.
In the long run, we believe Asia should continue to benefit from the shift towards higher value services-led growth, digital transformation and the ongoing financialisation across the region. Valuations look attractive in comparison to developed markets like the US, while low ownership of Asian equities in global portfolios provides a good backdrop for absolute returns as global liquidity flows eastwards.
As markets start to broaden from their narrow focus on AI, we believe quality businesses owned in the portfolio should do well. We have invested in companies with high-quality management who think long term and counter-cyclically, operating in industries with deep moats that support predictable and strong returns on capital. They are running businesses with solid pricing power due to strong brands, high switching costs, or strong network effects, and with conservative balance sheets where cash exceeds debt. We are confident that their strong fundamentals will translate into attractive shareholder returns in the long run.
Latest insights from the FSSA team
We have written short articles on companies, investment trends and market themes across our various strategies, which are available to read on the FSSA website.
Our latest piece “Against the current” discusses the reasons why high-quality companies are being overlooked amid the artificial intelligence boom and resurgence in cyclical stocks. FOMO is beating fundamentals; but these trends are creating opportunities for quality-focused investors in Asia and emerging markets to accumulate attractive businesses at lower valuations.
Source for company information: First Sentier Group and company data. This stock information does not constitute any offer or inducement to enter into any investment activity. Portfolio data shown is from representative strategy accounts of the strategy shown above. Named new investments disclosed relate to holdings with a portfolio weight over 0.5%. It is not a recommendation or solicitation to purchase or invest in any fund. Differences between the representative account-specific constraints, currency or fees and those of a similarly managed fund or mandate would affect results.
Strategy update: Q4 2025
Asia Pacific All Cap strategy update: 1 October - 31 December 2025
In November 2025, First Sentier Group (FSG) announced a strategic transition of Stewart Investors’ (SI) investment management responsibilities to its affiliate investment team, FSSA Investment Managers (FSSA). This was decided to be in the best interests of our clients, given the significant overlap in SI’s and FSSA’s investment capabilities and our shared history and heritage.
Introducing FSSA Investment Managers
FSSA has been investing in Asia Pacific and Global Emerging Market equities since 1988 as part of the former Stewart Ivory & Company, which subsequently became First State Stewart. After years of organic growth, the First State Stewart team split in two in 2015, leading to the formation of FSSA Investment Managers and Stewart Investors.
Like SI, we are long-term and quality-focused investors. We pay little attention to the index or short-term performance, preferring to focus on generating absolute returns for our clients in the long run. From our research, we aim to construct relatively concentrated portfolios made up of the best ideas that we can find across Asia and emerging markets. As responsible, long-term shareholders, we have integrated sustainability analysis into our investment process and engage extensively with companies on environmental, labour and governance issues.
Following the transition of SI’s portfolios to FSSA, the Stewart Investors Asia Pacific All Cap portfolio is now being managed by Sree Agarwal and Martin Lau.
Sree Agarwal is a Portfolio Manager at FSSA Investment Managers. He joined the team in 2014 and focuses on India, Australia, and smaller companies research across the Asia region. Sree is the lead manager of the Scottish Oriental Smaller Companies Trust, and the FSSA Indian Subcontinent and FSSA Asian Opportunities strategies. Sree has more than 10 years of investment experience and is based in Singapore.
Martin Lau is one of the Managing Partners of FSSA Investment Managers. He has been with the team for more than 23 years (since 2002) and worked closely with members of the SI team before the 2015 reorganisation. He is a well-known and experienced investor and is lead manager of a number of FSSA strategies, including FSSA Asian Equity Plus, FSSA Asia Focus, FSSA China Growth and FSSA Hong Kong Growth. Martin has more than 30 years of investment experience and is based in Hong Kong.
Sree and Martin are supported by a broader team of investment analysts, with an average of 14 years of investment experience and 8 years tenure with the team. All 15 members of the FSSA investment team are analysts first and foremost, including the portfolio managers, and we spend the majority of our time meeting companies, writing research and seeking quality companies to invest in.
How we invest
FSSA’s investment philosophy, which shares its genesis with SI, has remained broadly unchanged since the First State Stewart team was established in 1988. We focus on identifying quality companies, buying them at a sensible price and holding them for the long term. Most importantly, we invest our clients’ capital as if it were our own. As long-term investors and owners of businesses on behalf of our clients, we look for founders and management teams that act with integrity and risk awareness, and dominant franchises that have the ability to deliver sustainable and predictable returns over the long term.
As a team, we conduct over 1,000 direct company meetings each year across Asia and other emerging markets. The most significant source of investment ideas comes from these company visits and country research trips. We find that our reputation as patient, long-term investors has given us unparalleled access to management, which allows us to gain valuable insights and a thorough understanding of the businesses we want to invest in.
As a result of our long-term time horizon and conservative investment approach, our portfolios – and our performance – can look very different to the index. We shy away from “flavour of the month” themes (such as the current AI-driven boom), and instead look for high-quality companies that can deliver attractive returns for much longer than the market expects – and extend our investment time horizon to capture that advantage. When you own quality businesses, time isn’t a risk – it’s an asset.
Our performance may lag in very buoyant or momentum-driven markets, but we usually compensate very quickly once such bubbles burst. Based on historical data, our long-term track record shows that our portfolios tend to perform better in “normal” markets (-15% to +15% returns over one) and bear markets (more than 15% decline), than in steeply rising markets (defined as over 15% returns over one).
A smooth transition
Given the significant overlap in SI’s and FSSA’s investment philosophy and portfolios, we know all the holdings well. As part of the transition, we made a few changes to tilt the portfolio towards companies with stronger cash generation, higher returns and better long-term growth prospects. In general, we are adding to holdings in China, where we have found leading businesses like Tencent, with strong competitive advantages and attractive growth at reasonable valuations. We are reducing exposure to India, mainly in cyclical businesses like Tube Investments of India and Motilal Oswal, where valuations are expensive and the growth outlook has deteriorated.
Below, we highlight a few of the key additions and disposals over the fourth quarter of 2025.
New purchases:
Tencent Holdings is the largest social media network and online gaming company in China, with growing businesses in online advertising, cloud services, e-payments/e-commerce and overseas gaming. Tencent has created an ecosystem of businesses which are unrivalled and should continue growing over the medium term. It has continued to develop new functions within WeChat (such as Video Accounts and Mini Shops), which should slowly improve monetisation and enhance the quality of the franchise. At FSSA, we have been shareholders of Tencent since 2005 and have consistently found the management to be effective long-term stewards of the business. In recent times, we have been impressed by Tencent’s AI strategy and its disciplined approach to technology investments, which aligns with our conservative view on AI capex spending.
Realtek is an integrated circuits (IC) design company based in Taiwan which focuses on connectivity solutions such as WiFi, Ethernet and Bluetooth. While wireless technology is relatively mature and seemingly commoditised, there does seem to be some differentiation between providers. With rising competition from Chinese chip designers who often undercut on price, Realtek is focusing more on value-added products and has targeted applications with higher tech requirements, such as Edge-AI devices and AI glasses. We are optimistic that Realtek will be able to fend off the competition with higher barriers to entry as it moves up the value chain, and that margins should improve due to the product mix. The company has a long history and good track record and should benefit from the broadening use of AI in on-device AI agents.
Kotak Mahindra Bank (KMB) is one of India’s leading financial services companies – it has consistently improved the strength of its deposit franchise and maintained better asset quality than peers through the business cycle. While the founder, Uday Kotak, has stepped down from his managing director/CEO role due to the central bank’s limits on leadership terms, he remains closely involved as a board director and should ensure that the bank’s risk awareness and long-term thinking is maintained. Meanwhile, the new CEO (Ashok Vaswani) aspires to grow the business further by focusing on consumer banking and digitisation. We expect to see a growing trend of formalised financial savings, benefiting KMB’s insurance, mutual funds and asset management businesses.
Complete sales:
Samsung Biologics is a leading contract manufacturing organisation (CMO) in biologics. An impressive franchise that grows strongly (25%+ p.a.) at high margins (40% operating margins), but it is fundamentally capital-intensive and somewhat commoditised. We sold on concerns about rich valuations and its large market capitalisation.
Motilal Oswal Financial Services is a non-bank financial company (NBFC) in India. We sold out of a lower conviction holding to raise cash for better ideas elsewhere.
Glodon is a leading construction software vendor in China. We have known the company for many years. The challenges related to the property sector mean that the growth outlook is unattractive. Based on the current near-term weakness, we believe the valuation does not adequately account for the risks.
Performance and outlook
With our long-term investment time horizon, we tend not to pay much attention to short-term market fluctuations. We invest on at least a three-to-five-year view, though we often hold on to companies for much longer. In an industry rife with short-termism, we believe our long-term approach stands out from the crowd.
What we have seen, over the past few decades, is that average holding periods for stocks have fallen from over eight years in the 1960s to less than six months today. Yet this shift has come at a cost: it reduces investors’ ability to generate outsized returns that are materially different from the broader market. The reason is simple — as investment horizons shrink, so does the return dispersion between the best- and worst-performing companies. With less time in the market, investors end up tracking the index, not beating it.
Emerging Markets: time horizons matter
MSCI EM Index -dispersion around mean return for top 10% top / bottom stock performers
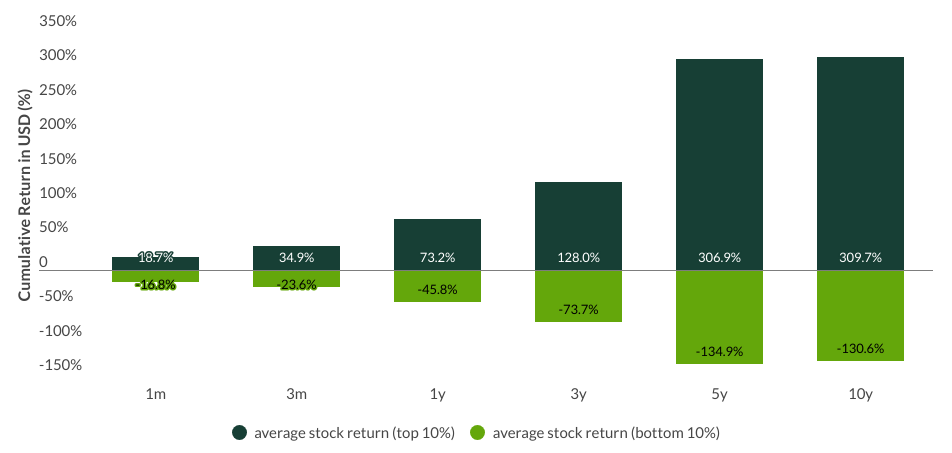
Source: MSCI Emerging Markets Index, as at 31 May 2025
In a world where markets rise consistently, that might seem like an acceptable outcome. But markets don’t move in straight lines; and in addition to the higher costs and transaction fees that come with frantic trading activity, the bigger issue is that investors miss out on what is far more important – the future value creation that the best companies tend to generate. This is often poorly understood by the market, with many investors simply focusing on the next quarter or year ahead. Yet the real drivers of returns lie in the cash flows that come well beyond that timeframe.
With that context in mind, we highlight the key contributors and detractors from performance over the fourth quarter of 2025.
The largest contributor to performance over the period was Samsung Electronics, a leading manufacturer of memory and semiconductor chips. In recent years, Samsung’s foundry business has been a major point of investor concern, which culminated in significant losses in the first half of 2025. These losses were exacerbated by one-time charges related to US export controls to China. The company has since undertaken a strategic shift from a “capacity-first” to a “customer-first” model, which appears to be bearing fruit. The shares rose during the quarter, as Samsung continued to benefit from surging AI-related demand for its high-bandwidth memory chips as well as tightness in traditional DRAM demand-supply. Strong results from US chipmaker Micron reinforced expectations of a sustained memory upcycle into 2026. With the turnaround in its foundry business and a strong legacy memory business, we believe the risk-reward looks favourable.
Taiwan Semiconductor Manufacturing (TSMC) was the second largest contributor to performance, as it continued to see solid revenue growth and strong demand from cloud AI for its leading-edge chips. Given the lead time and supply shortages, this provides visibility into 2026 earnings and possibly even beyond into 2027. TSMC is expected to invest in capacity expansion, with top line growth to follow.
The third largest contributor to performance was DFI Retail, a leading pan-Asian retailing group with a dominant market position across various segments, including drug stores, supermarkets, convenience stores, IKEA and Maxim’s (a joint venture catering and restaurants business). After years of lacklustre performance, DFI – and the broader Jardine group – has redoubled efforts to grow the business, and to improve operational efficiencies and returns on capital while optimising capital allocation. Improving total shareholder return is the new mantra for the group, and there are now clear signs of improvement. We believe margins could improve still further and lead to underlying profit growth.
On the negative side, Alibaba was the largest detractor from performance. The shares weakened over the last few months of 2025 on concerns about its e-commerce business and the resulting pressure on earnings. Losses from its Taobao Instant Commerce business (food delivery and on-demand retail) weighed on the share price. On the other hand, Alibaba has had a strong run-up over 2025, driven by its investments into AI and growing demand for cloud computing. Alicloud revenue has accelerated in recent quarters and is expected to continue at pace in the coming quarters.
Tube Investments of India was the second biggest detractor, as it reported sluggish business performance and rising competition in the electric vehicle (EV) space. Despite its early mover advantage, Tube has struggled to maintain market share. It plans to arrest these challenges by increasing the number of dealership partners and entering new sub-segments in EV battery packs. On a positive note, the core business is stable with robust returns on capital employed, and it generates healthy free cash flow which is being invested in new businesses with high returns potential. In this endeavour, we are backing the management, particularly Vellayan Subbiah (executive chairman), who has an exceptional track record and has created tremendous value for shareholders.
Sea Ltd was the third largest detractor, as it continued to decline on concerns about margins, given its marketing tactics and promotional spending. Shopee, its e-commerce platform, has expanded its VIP program to Singapore and Taiwan (in addition to Indonesia, Malaysia, the Philippines, Thailand and Vietnam), which includes extra cash-back, monthly discount vouchers and free delivery – all for a fixed monthly subscription fee.
Looking forward
We are optimistic on the outlook for Asian equities. With a rising share of global gross domestic product (GDP) growth, Asia should continue to benefit from the shift towards higher value services-led growth, digital transformation and the financial activities across the region. Valuations also look attractive in comparison to developed markets like the US, while low ownership of Asian equities in global portfolios provides a good backdrop for positive returns.
Across the team’s Asian equity portfolios, our core holdings have continued to deliver good underlying business performance and shareholder returns. Current portfolio valuations remain attractive – as they have been over the last couple of years. Looking forward, we expect earnings to grow at low double-digit rates with circa 20% average returns on equity, while companies are generating more cash and returning it to shareholders.
While we can’t second guess when the AI theme might run its course, our holdings are characterised by strong competitive advantages, and they have historically managed to preserve margins and profitability through the cycles. We are confident that their strong fundamentals will translate into attractive shareholder returns in the long run, as the market broadens, over time, from its narrow focus on AI.
SFDR Article 9 and FSSA’s approach to sustainability
All SI portfolios will continue to be managed true to label, with due consideration given to SI’s SFDR Article 9 sustainability requirements. Importantly, both FSSA and SI had operated as one team for 27 years (1988-2015) before the decision was made in 2015 to split into two teams. This is heavily reflected in our investment philosophies and processes and our respective approaches to sustainability.
At FSSA, we believe it is everyone’s responsibility to think about sustainability as part of his or her investment decision-making. We don’t use external consultants or environmental, social and governance (ESG) ratings, nor do we outsource the sustainability work to a separate team. In our research, we focus on evaluating the long-term merits of a given investment opportunity. Given that sustainability issues are effectively investment issues, we believe that these challenges and opportunities – and management’s response to them – can have a significant impact on a company’s returns. As such, we look for evidence that the management operates the business effectively and in the interests of all stakeholders – both now and for the longer term.
While issues relating to climate change, or people and communities, are often the ones that get the most attention, most of our company engagements relate to management quality and corporate governance systems, as we believe that good governance is the foundation on which great companies are built. We often engage with management teams on capital allocation and strategy, remuneration structures and succession planning, board diversity and tenure, and ensuring high levels of transparency and company disclosure – to highlight just a few.
For more information on FSSA, or if you have any questions about the transition, please do not hesitate to contact us.
NB Both Stewart Investors and FSSA have been supported by the same centralised Responsible Investment team within the First Sentier Group, who will continue to support FSSA after the transition of SI funds.
Source for company information: First Sentier Group and company data. This stock information does not constitute any offer or inducement to enter into any investment activity. Portfolio data shown is from representative strategy accounts of the strategy shown above. Named new investments disclosed relate to holdings with a portfolio weight over 0.5%. It is not a recommendation or solicitation to purchase or invest in any fund. Differences between the representative account-specific constraints, currency or fees and those of a similarly managed fund or mandate would affect results.
Portfolio Explorer
Portfolio Explorer tells the stories of the companies we invest in. The company profiles have been written by our own team so that you can see why they believe that the companies they invest in are making the world a better place.
Fund data and information
Fund prices and details
Click on the links below to access key facts, literature, performance and portfolio information for the funds and share classes available in this jurisdiction:
Stewart Investors Asia Pacific All Cap Fund
| Fund name | Fund type | Currency | Price | Daily change | Price date | Factsheet |
|---|---|---|---|---|---|---|
| Stewart Investors Asia Pacific All Cap Class I (Acc) | Irish UCITs | EUR | 13.96 | -1.40 | 30 Oct 2026 | |
| Stewart Investors Asia Pacific All Cap Class I (Acc) | Irish UCITs | SGD | 11.11 | -1.25 | 30 Oct 2026 | |
| Stewart Investors Asia Pacific All Cap Class I (Acc) | Irish UCITs | USD | 12.47 | -0.95 | 30 Oct 2026 | |
| Stewart Investors Asia Pacific All Cap Class VI (Acc) | Irish UCITs | EUR | 4.29 | -1.40 | 30 Oct 2026 | |
| Stewart Investors Asia Pacific All Cap Class VI (Dist) | Irish UCITs | GBP | 11.25 | -1.74 | 30 Oct 2026 | |
| Stewart Investors Asia Pacific All Cap Class VI (Acc) | Irish UCITs | USD | 16.82 | -0.95 | 30 Oct 2026 |
Share prices are calculated on a forward pricing basis which means that the price at which you buy or sell will be calculated at the next valuation point after the transaction is placed. Where a fund price is marked XD, this means that the fund is currently Ex-Dividend. Past performance is not necessarily a guide to future performance. The value of shares and income from them may go down as well as up and is not guaranteed. Please note that the yield quoted above is not the historic yield. It is considered that the yield quoted represents the current position of investments, income and expenses in the fund and that this is a more accurate figure. Investors may be subject to tax on their distribution. The yield is not guaranteed or representative of future yields. You should be aware that any currency movements could affect the value of your investment. The Funds within the First Sentier Investors Global Umbrella Fund plc (Irish VCC) are denominated in USD or EUR.
Following the UK departure from the European Union, the First Sentier Investors ICVC, an open ended investment company registered in England and Wales ("OEIC") has ceased to qualify as a UCITS scheme and is instead an Alternative Investment Fund ("AIF") for European Union purposes under the terms of the Alternative Investment Fund Managers Directive (2011/61/EU). Accordingly, no marketing activities relating to the OEIC are being carried out by Stewart Investors in the European Union (or the additional EEA states) and the OEIC is not available for distribution in those jurisdictions. We have made documents available for existing EU investors in the ICVC which can be accessed here.
Strategy and fund name changes
As of end of 2024, please note that Stewart Investors strategies and the Funds within the UK First Sentier Investors ICVC, First Sentier Investors Global Umbrella Fund plc (Irish VCC) and First Sentier Investors Global Growth Funds (Singapore Unit Trust) have been renamed. Please refer to our note via the link below for further information.

An affiliate of First Sentier Group
Copyright © 2026 Stewart Investors.